Architect capital on their your terms.
The operator's guide to term sheets, waterfalls, and investor psychology — so the next document you sign is one you wrote.
The clause that wiped out a $3.4M promote.
Most operators don’t lose equity during disputes. They lose it three years earlier, in a sentence they didn’t challenge during term sheet review.
The "Standard" Draft
An operator raising $14M for a 280-unit Raleigh multifamily asset accepted this clause in § 8.4 of the joint venture agreement. His attorney noted it as "institutional boilerplate."
“Upon an Event of Default or failure to meet the Minimum Debt Service Coverage Ratio of 1.25x for two consecutive quarters, Member Loans shall accrue interest at 18% per annum, compounding monthly, and shall take absolute distribution priority over any General Partner promote distributions until satisfied in full.”
Four ways operators surrender their equity before the close.
Capital transactions fail in predictable patterns. The manual documents each failure mode with historical precedent and counter-language.
The Supplicant Posture
Presenting deals designed for the wrong mandate.
Operators often pitch deals based on how badly their company needs growth capital. But institutional allocators are not charities; they evaluate incoming deals against specific mandate constraints, concentration limits, and underwriting templates.
Deals rejected not because of asset quality, but because the check size fell outside the mandate threshold.
Covenant Drag & Priority Shift
Technical defaults triggered by external macro shocks.
Lenders and preferred equity investors often insert debt service coverage ratios or liquidity floors that can trip during macro rate fluctuations—even when the underlying asset is cash flowing and fully occupied.
A 250 bps rate hike transforms a healthy asset into an emergency recapitalization event.
Liquidation Preference Wipeouts
Participating preferred tiers that consume common equity.
When capital enters with multiple liquidation preferences and compounding dividends, founders and common equity holders discover at exit that the sale price did not clear the senior preference stack.
The FanDuel transaction, where early founders and employees saw common shares valued at $0 despite a $465M sale.
Springing Bad Boy Carve-Outs
Non-recourse commercial debt becoming personal liability.
Standard non-recourse carve-out guaranties often contain loose "insolvency" or "waste" triggers where involuntary filings or subordinate liens trigger full recourse against the sponsor's personal balance sheet.
Involuntary bankruptcy filings by unpaid subcontractors converting commercial loans into personal judgments.
“Allocators don’t allocate to need. They allocate to structure.”
Where does your current posture sit?
Five diagnostic questions to evaluate whether you enter negotiations as a supplicant or as a sovereign architect.
When an institutional allocator asks "Who else is currently in the round or tranche?", how do you respond?
Inside the Manual.
The Psychology of Capital
“Allocators do not fund businesses; they fund mandates.”
The Architecture Premise
Why capital is not scarce, the Charlotte origin story, and how allocators triage incoming deal flow before the first slide is opened.
Allocator Psychology & The 4 Postures
The difference between family offices, institutional credit funds, and high-net-worth syndicates. How to diagnose allocator risk constraints.
The Mandate Match
Structuring transactions so they fit cleanly into an allocator’s balance sheet guidelines rather than requiring an investment committee exception.
The book teaches the method. Capital Architect AI runs it on your documents.
The book teaches the method. Capital Architect AI runs it on your documents.
Term Sheet Review
Analyzes operating agreements, debt terms, and joint venture drafts against the Four Vectors to flag punitive dilution, liquidation preference traps, and springing covenants.
Waterfall & Promote Modeling
Models American vs. European waterfall distributions, hurdle structures, and capital call dilution so you can evaluate promote outcomes before signing.
Clause Library & Redlines
Reference clauses and counter-language for priority member loans, non-recourse carve-out defense, and clawback limitation terms.
Capital Architect AI is currently in closed early access. Access opens when the founding batch begins. Founder's Bundle buyers receive 3 months included upon launch plus grandfathered founder pricing.
Order your copy.
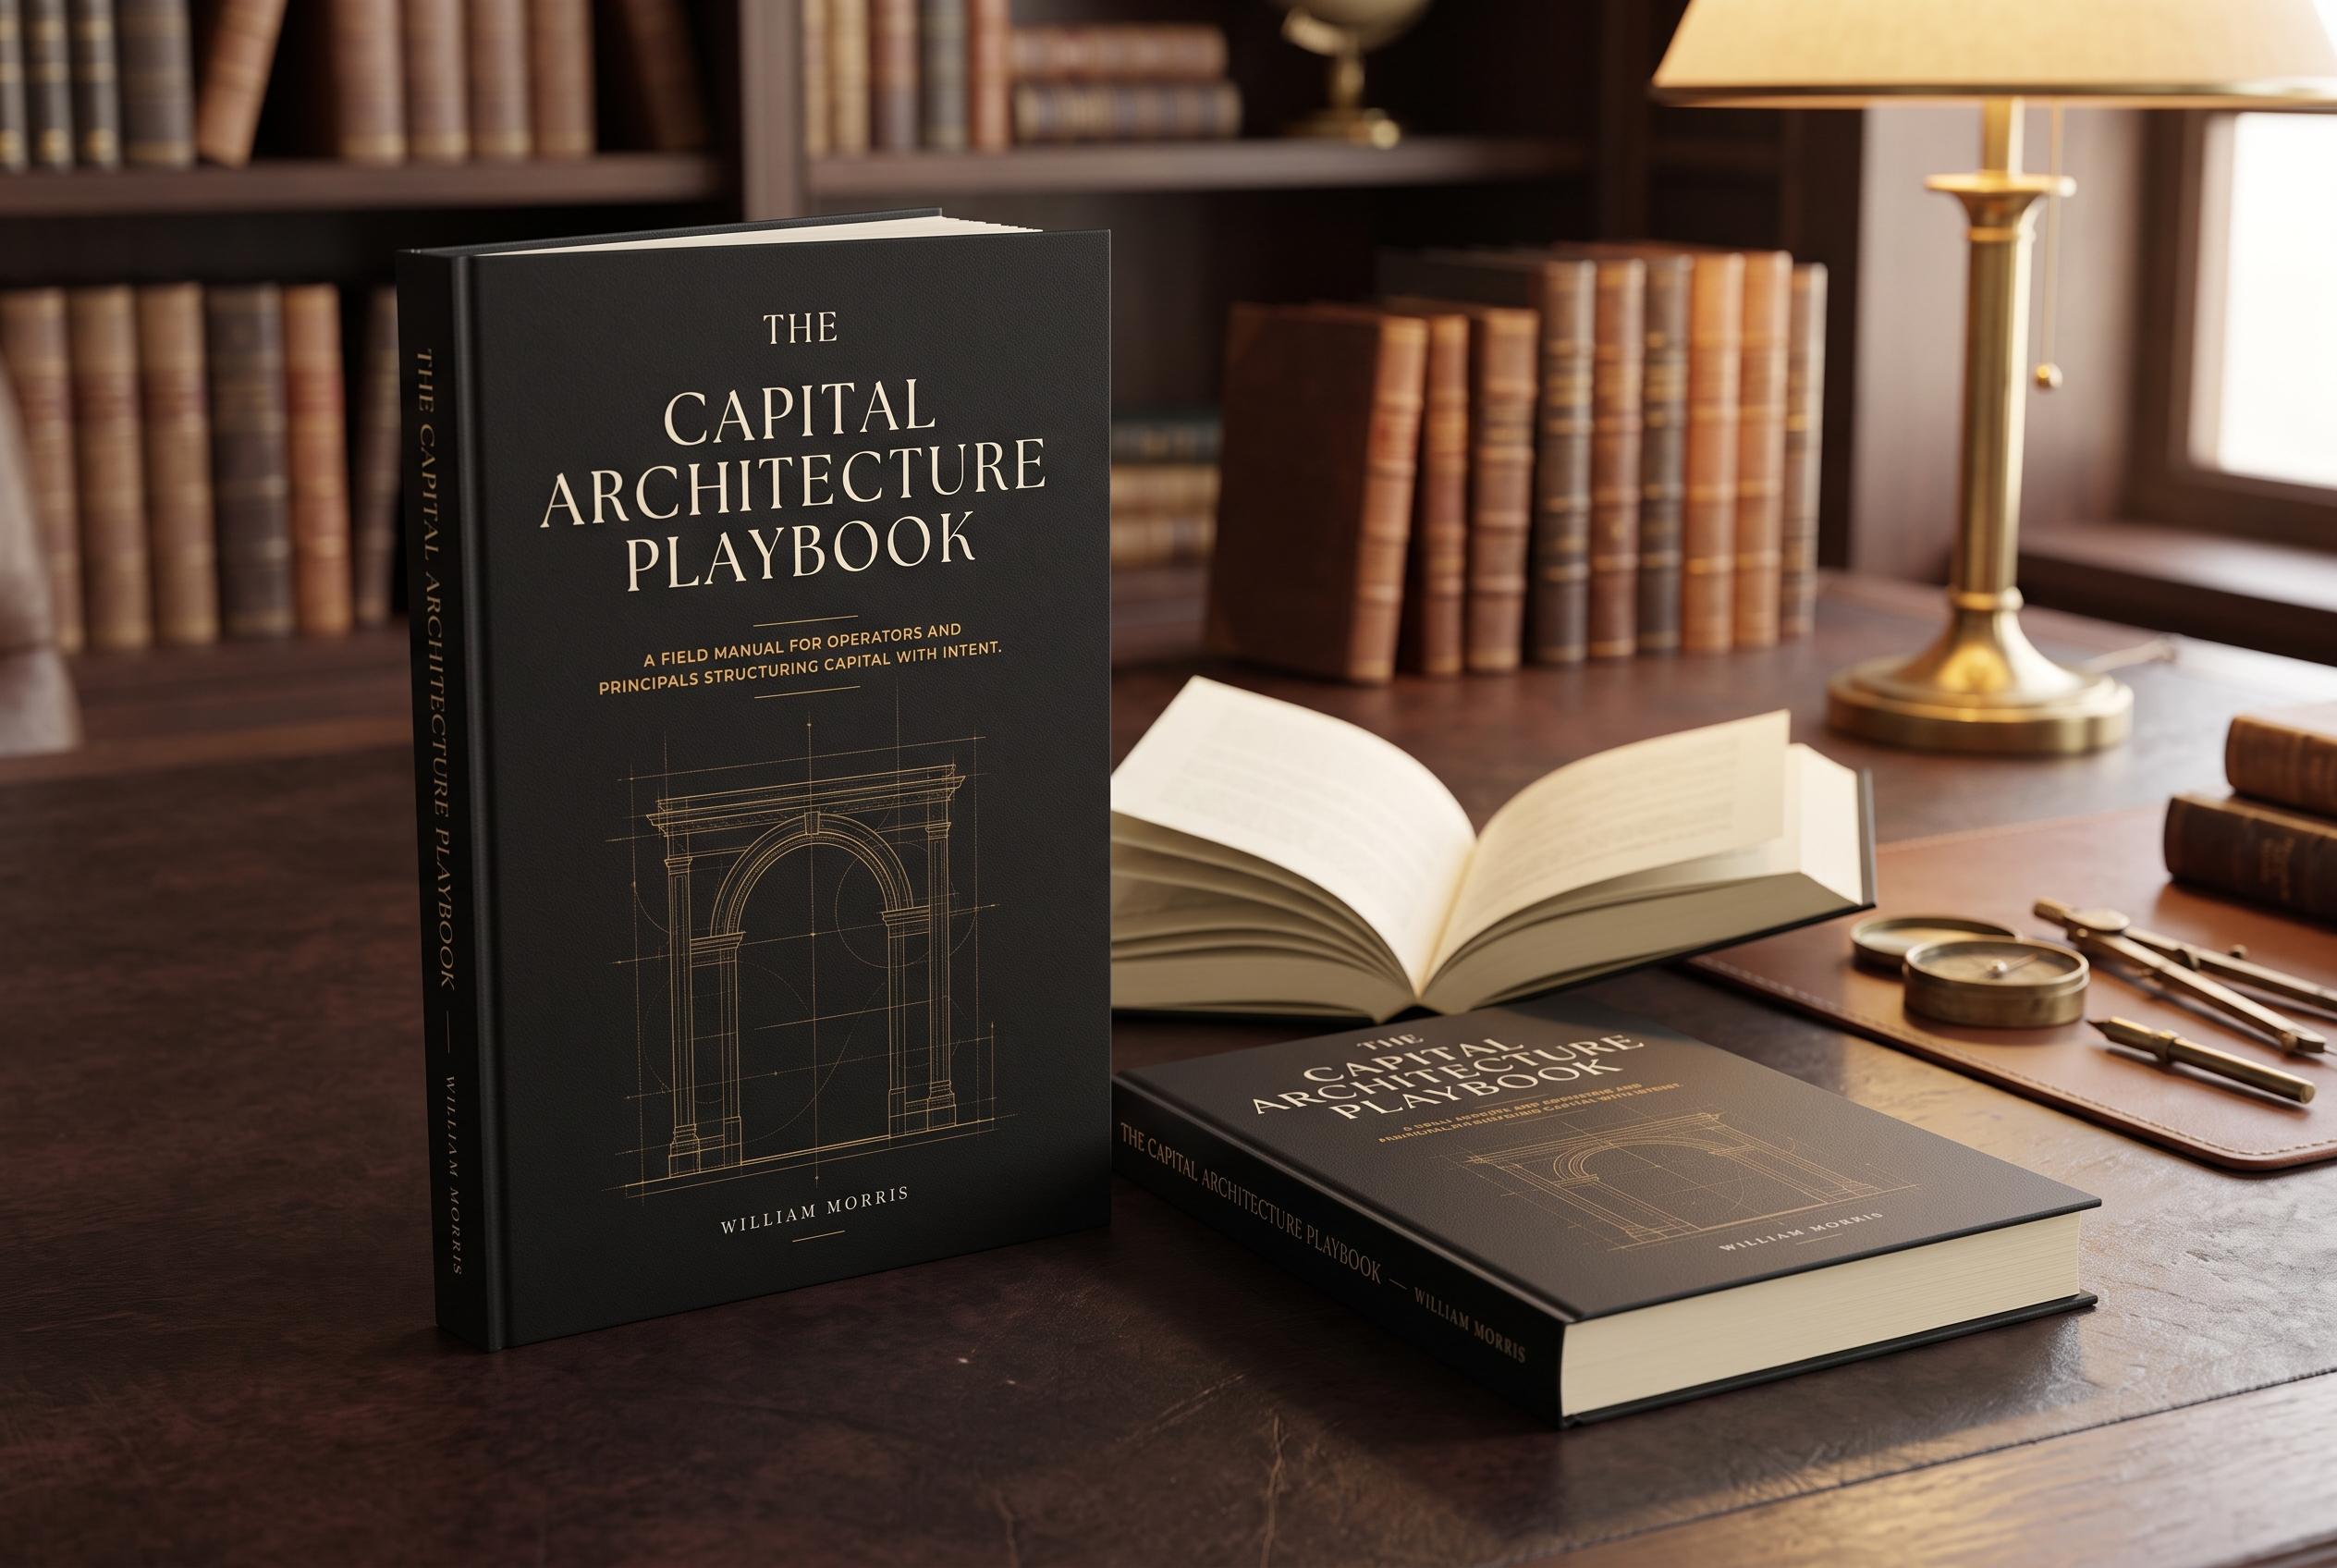
Every physical paperback is personally signed and inscribed by William Morris in Knoxville, TN, and includes the instant PDF edition at no extra charge.
Digital Edition
Instant download · PDF
Complete 253-page manual for screen and tablet
Searchable, DRM-free PDF edition with active cross-references and printable audit checklists.
Signed Paperback
Most chosenShips in 1–2 business days · Free US shipping · PDF instantly
Hand-signed and inscribed by William Morris in Knoxville, TN
Physical 253-page 6" × 9" paperback, personalized inscription, plus the instant PDF included free.
Put the same manual in your partner's hands so you review drafts and evaluate term sheets from the same baseline.
Founder's Bundle
Founding accessShips in 1–2 business days · PDF & digital tools instantly
Signed book + instant PDF + 3 months of Capital Architect AI + templates
For operators actively preparing an offering, negotiating an LOI, or structuring a raise in the coming months.
The Sovereign Operator 30-Day Guarantee
Read it for 30 days. If it isn't worth far more than you paid, email me and I'll refund every dollar. Keep the book.
Direct Order vs. Amazon.
If you need the book tomorrow afternoon, Amazon Prime is faster. If you want a signed copy with the PDF included free, order direct from Knoxville.
| Dimension | Direct From Author ($29) | Amazon Paperback |
|---|---|---|
| Hand-Signed & Personalized | Yes — signed & inscribed by William Morris | No — standard automated print fulfillment |
| Instant PDF Edition | Included free today (read immediately while book ships) | Not included (must purchase separately on Kindle) |
| Direct Author Email Channel | Direct line to will@CapitalArchPlaybook.com for deal questions | No direct contact |
| Delivery Transit Time | 3–5 business days via USPS Priority Mail | 1–2 days via Amazon Prime (faster transit) |
Frequently Asked Questions.
Yes. The underlying mechanics of private capital are consistent across asset classes. Chapter 4 examines venture and growth equity structures (liquidation preferences, drag-alongs, protective provisions), while Chapter 5 analyzes private equity and real estate mechanics (waterfall hurdles, GP promote catch-ups, debt covenants, and non-recourse carve-outs). If you raise private capital, the principles apply.
The next term sheet is coming. Read this first.
Before you negotiate your next waterfall, sign a debt covenant, or grant an investor side letter, put these structural mechanics on your desk.